How the Calculation Actually Works
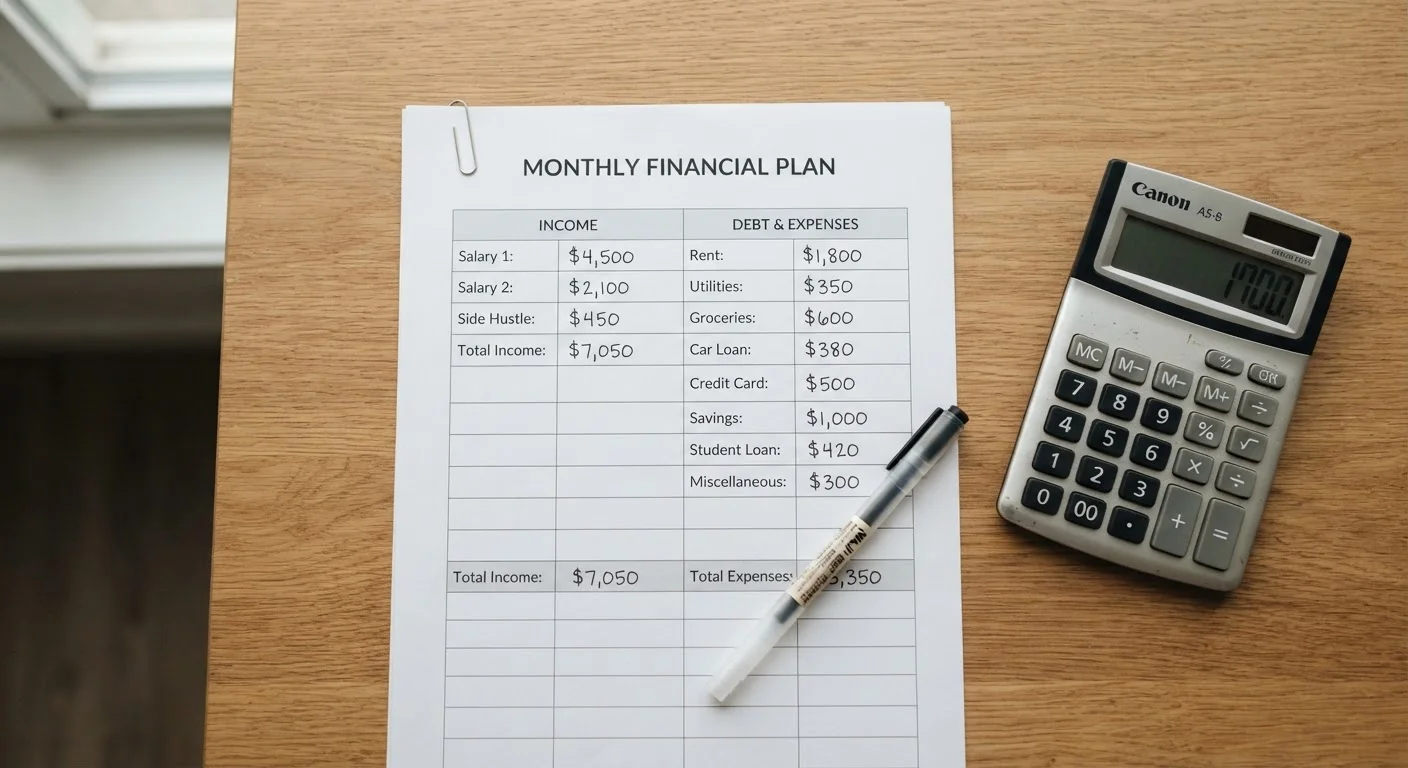
The math behind DTI is straightforward. Add up all your required monthly debt payments - mortgage or rent, car loans, student loans, minimum credit card payments, and any other installment obligations. Then divide that total by your gross monthly income (what you earn before taxes). Multiply by 100 to get a percentage.
For example: if your monthly debt payments total $1,800 and your gross monthly income is $6,000, your DTI is 30%. That's within the range most lenders find acceptable.
One important detail: gross income is used, not take-home pay. That means your DTI will look more favorable on paper than it might feel day-to-day, since your actual spendable income after taxes is lower. This is worth keeping in mind when assessing your own financial comfort, not just your lender eligibility.
43%
Maximum DTI for most conventional mortgages
The Consumer Financial Protection Bureau identifies 43% as a common DTI ceiling for qualified mortgage eligibility under standard lending guidelines.
36%
DTI threshold considered financially healthy
Many financial planners and lenders use 36% as a benchmark for a manageable debt load, leaving room for savings and unexpected expenses.
2 levers
Ways to improve your DTI
Reducing total monthly debt payments or increasing gross income are the only two ways to lower your DTI - there are no shortcuts.
Why Lenders Pay Close Attention to It
DTI gives lenders a fast read on repayment risk. Someone earning $10,000 a month with $1,500 in debt obligations looks very different from someone earning $4,000 with the same payment load - even though the dollar amounts are identical. DTI normalizes debt burden relative to earning power.
For mortgage lending specifically, DTI thresholds carry real weight. Many conventional loan programs require a DTI at or below 43% for approval, and borrowers with DTIs below 36% tend to receive the most favorable terms. You can read more about how mortgage lenders apply these thresholds in our article on how lenders use DTI in home loan decisions.
Beyond mortgages, DTI influences approvals for auto loans, personal loans, and even some credit card applications. A lower DTI signals that you have breathing room in your monthly budget - reducing the lender's risk that a financial disruption will cause you to miss payments.
A teacher earning $5,500 per month gross has a car loan payment of $350, a student loan payment of $300, and a minimum credit card payment of $75 - totaling $725.
A freelancer earns $7,000 per month but carries a mortgage of $1,800, a car payment of $550, student loans of $400, and credit card minimums of $250 - totaling $3,000 per month.
A couple is considering refinancing their home but recently took on an auto loan, pushing their combined DTI from 31% to 41%.
DTI as a Personal Finance Signal, Not Just a Lending Hurdle
It's easy to think of DTI purely as a gatekeeping metric - something lenders check before saying yes or no. But it's also a useful self-assessment tool. Tracking your own DTI over time reveals whether your debt load is growing faster than your income, which is an early warning sign worth taking seriously.
DTI doesn't tell you everything. It doesn't capture your savings rate, emergency fund balance, or total assets. That's why it pairs well with measures like net worth, which reflects your full financial picture rather than just monthly cash flow pressure.
It's also worth distinguishing between types of debt. A mortgage payment and a high-interest credit card balance both count toward DTI, but they don't carry the same long-term implications. Understanding the difference between productive and harmful debt helps you interpret your DTI more meaningfully - not just as a number, but as a signal about your financial structure.
If your DTI is climbing and debt is starting to feel less manageable, it may be worth reviewing warning signs that debt is becoming a structural problem rather than just a month-to-month inconvenience.
This article is for general informational purposes only and does not constitute personalized financial, tax, or legal advice. Consult a licensed financial professional for guidance specific to your situation.